Charlotte Home Sales Fell in August. Here's What That Means If You're Buying or Selling This Fall
Closed sales across the Charlotte region dropped 8.7% in August while mortgage rates climbed past 7%. But prices are holding, inventory is up, and buyers have more room to negotiate than they've had in years.
Charlotte region
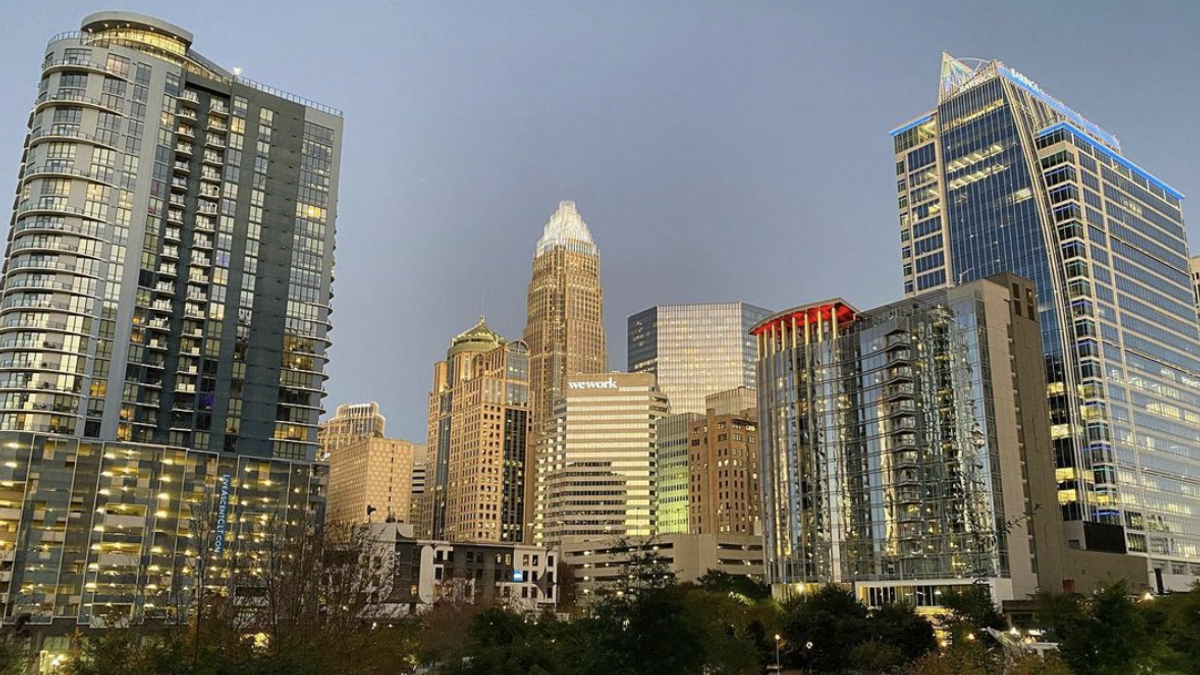
Charlotte's housing market cooled noticeably at the end of summer. Closed home sales across the 16-county region fell 8.7% from a year earlier in August, to 3,560 homes, according to the Canopy Realtor Association's latest monthly report, as reported by WSOC-TV and the Charlotte Business Journal.
That headline number sounds dramatic, and mortgage rates have only climbed since. But if you dig into the rest of the report, the picture is more mixed than a single percentage suggests. Here's what happened, why it happened, and what it means for you depending on which side of the closing table you're on.
The August numbers
Every major measure of activity slipped in August, both compared with last year and compared with July.
Closed sales dropped 8.7% year over year and about 14% from July. Pending contracts, which tell you where closings are headed next, fell 1.8% to 3,763. New listings declined 2.2% to 4,940, so fewer sellers put homes on the market, too.
Prices, however, did not fall. The regional median sales price came in at $427,500 in August, up 0.6% from a year earlier, according to Canopy's report. That's a tiny gain, but it's a gain, and it's consistent with what Charlotte has seen all year: fewer sales, flat to slightly higher prices.
Why the slowdown?
The short answer is borrowing costs. The longer answer is that buyers are being more careful about everything.
Canopy's 2026 president, Joan B. Goode, said in the report that affordability remains a major consideration and that buyers are becoming more selective as they weigh higher borrowing costs alongside their other household expenses.
Those borrowing costs have moved sharply in the wrong direction. Freddie Mac's weekly survey had the average 30-year fixed rate near 6.7% through most of August. By Sept. 24, it crossed 7% for the first time since January 2025, and as of Oct. 1 it averaged 7.28%. A year earlier, that same rate was 6.34%.
Here's what that difference looks like in real money. On a home at Charlotte's August median price with 10% down, the monthly principal and interest payment is roughly $2,392 at 6.34%. At 7.28%, it's about $2,633. That's around $240 more every month, before taxes and insurance, for the exact same house.
Most of the August contracts that turned into September and October closings were signed before rates jumped past 7%. That's why many local agents expect the fall numbers to stay soft.
The part of the story that gets overlooked
Here's where the report gets more interesting, especially if you're shopping for a home.
Buyers have more choices. Active inventory across the region grew 7.1% from a year ago to about 13,574 homes, according to Canopy. That works out to roughly 3.7 months of supply. A market is generally considered balanced at around six months, so Charlotte still leans toward sellers on paper. But 3.7 months is a real shift from the bidding-war years, when homes were often gone in a weekend.
The year as a whole is steady. Canopy noted that activity through the first eight months of 2026 remains on par with 2025. Year-to-date closed sales are down about 1.1%, and pending contracts are actually running slightly ahead of last year. One weak month doesn't erase that.
The South Carolina side is behaving differently. In York, Lancaster, Chester, and Chesterfield counties, closed sales fell 13.3% in August, but pending contracts rose 1.8%. New construction made up about 22% of contract activity there. If you've driven through Fort Mill, Indian Land, or Lancaster County lately, you've seen why. Builders are filling a big share of demand, and many are using rate buydowns and closing cost incentives that resale sellers can't always match.
What this means if you're buying
This is a better negotiating environment than Charlotte buyers have had in several years. More inventory means more time to compare homes and more room to ask for things like seller-paid closing costs, repairs, or a temporary rate buydown.
The tradeoff is the rate. Before you start touring, get a current preapproval and ask your lender to run your payment at today's rate, not last month's. Rates are updating weekly right now, and a quarter point can change what price range makes sense for you.
If you're looking at new construction, ask every builder what incentives are on the table and compare the total cost, not just the sticker price.
What this means if you're selling
Prices are holding, which is good news. But buyers are more selective, and they have options. That means pricing correctly from the first day matters more than it did two years ago. A home that sits for a few weeks while comparable homes nearby sell tends to lose leverage fast.
Condition matters, too. Homes that are clean, well presented, and move-in ready are still selling. Homes that need work are seeing longer timelines and more negotiation.
If you're competing with nearby new construction, especially in the South Carolina suburbs, be ready for buyers to ask what you can offer to keep up with builder incentives.
The bottom line
Charlotte's housing market isn't crashing. It's adjusting. Sales are slower, rates are higher, and prices are mostly holding where they've been. For buyers, that means more choice and more leverage, paired with a higher monthly cost. For sellers, it means the market still works, but it rewards getting the details right.
Canopy's September report is expected later this month, and it will be the first look at how the region responded once rates moved above 7%. We'll update you when it's out.
Last verified Oct. 8, 2026. Mortgage rates cited are Freddie Mac's weekly national averages and change every Thursday.